Renters’ Mover COI: Get Exact Building Wording Before Move Day
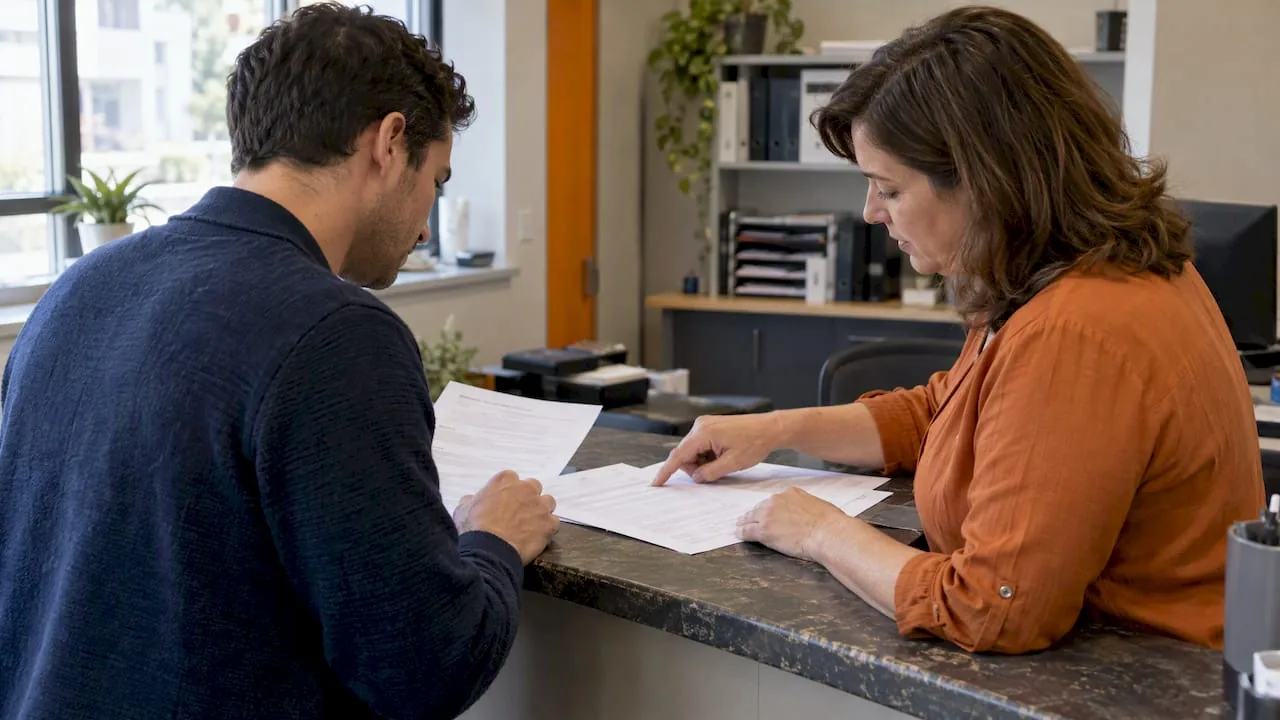
A mover’s certificate of insurance is proof the moving company carries the liability and workers’ compensation coverage the building requires. It protects the building, not your belongings. If your building asks for one and your mover doesn’t produce it, crews can be turned away at the door or denied elevator access on moving day, so it pays to request the building’s exact requirements early and get the certificate issued at least 24 to 48 hours ahead.
TL;DR:
- Ask building management for a sample certificate or written requirements, including the exact holder name, address, coverage limits, and any endorsement or notice rules.
- Send the building’s sample to the mover’s insurance agent promptly; issuing a signed, typed certificate and requested endorsements usually takes 24 to 48 hours.
- A COI covers building damage and injuries, not belongings; interstate movers offer separate valuation choices, including released value at $0.60 per pound per item.
Table of Contents
- What a certificate of insurance for movers actually is
- Why buildings and property managers require a COI
- What a mover’s COI usually includes
- How to request and obtain an acceptable COI
- How to check a COI is acceptable
- How a COI differs from protection for your belongings
- How we handle COI requests for our customers
- Get your move booked with COI handling included
- FAQ
- Sources
What a certificate of insurance for movers actually is
A certificate of insurance, often called a COI, is a one-page summary that proves a business carries active insurance policies. Movers almost always use the standard industry form, known as ACORD 25, because property managers and building staff recognize its layout and know exactly where to look for the numbers that matter.
Three parties typically appear on the document:
- The producer: the insurance agency or broker that issued the certificate on the mover’s behalf.
- The insured: the moving company itself, listed by its exact legal business name.
- The certificate holder: the building, property management company, or HOA requesting proof of coverage.
What a COI is not matters just as much as what it is. The certificate documents the mover’s liability and workers’ compensation coverage, protecting the building’s property and people against damage or injury the move might cause. It has nothing to do with coverage for your sofa, your television, or your grandmother’s china. That protection, called valuation coverage, is a separate arrangement between you and your mover, governed by federal rules for interstate moves and spelled out on your bill of lading.
Why buildings and property managers require a COI
Property managers ask for a COI for one practical reason: if a mover’s crew damages a lobby wall, dents an elevator, or injures someone in a hallway, the building wants an insurer standing behind that mover, not an empty promise. Requiring proof of coverage before the move shifts financial risk away from the building and onto the moving company’s policy.
Operational concerns tend to drive stricter rules in certain buildings. Freight elevators with weight limits, polished marble lobbies, narrow stairwells, and tight loading docks all raise the odds of an expensive mishap, so high-rises and commercial properties frequently set tougher insurance thresholds than a single-family home ever would. Specific building types commonly enforce this:
- High-rise condos and co-ops with staffed lobbies and freight elevators.
- Commercial office buildings and retail centers with shared loading areas.
- HOAs with house rules that specify minimum coverage limits or exact certificate wording.
Some associations go further and write insurance language directly into lease agreements or house rules, specifying limits, additional insured status, or notice periods that a generic certificate won’t satisfy.
Pro Tip: Ask the building for a sample COI from a previous move, not just a list of requirements. A real example shows you the exact wording a mover’s insurance agent needs to match.
What a mover’s COI usually includes
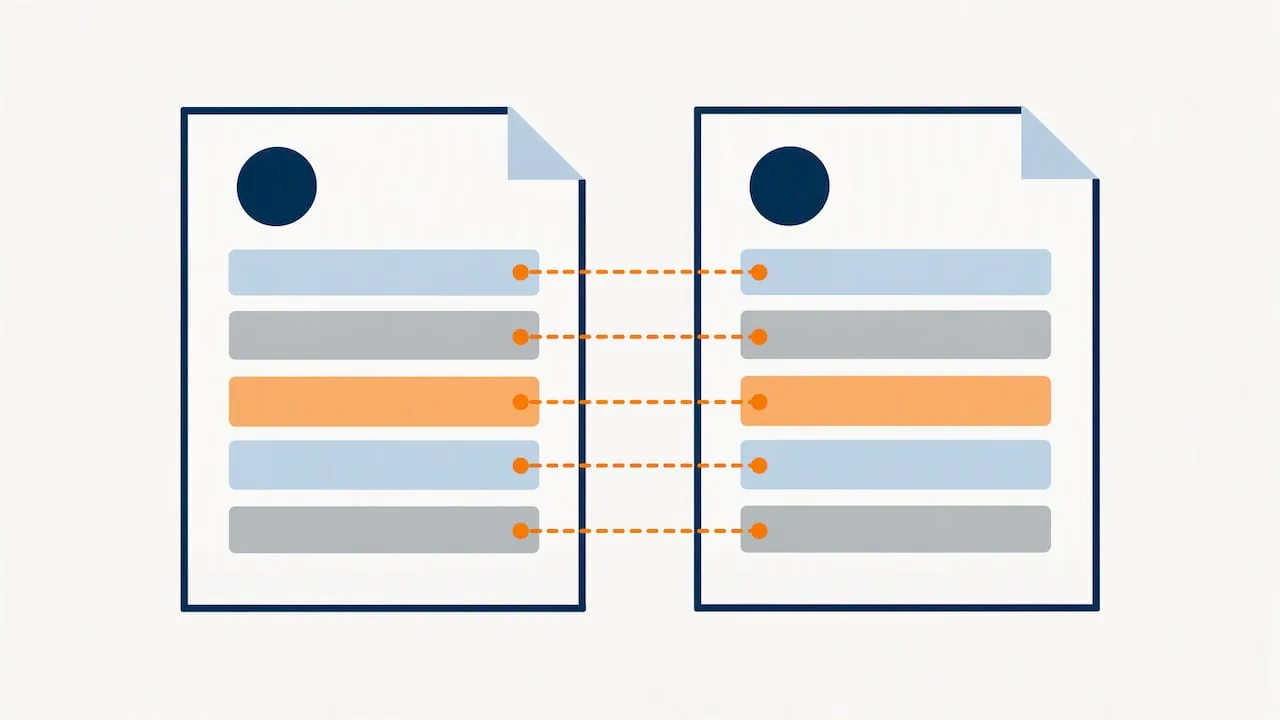
Most certificates built for moving companies list a predictable set of coverage lines, and knowing them helps you spot a complete certificate from an incomplete one at a glance.
- Commercial general liability, covering property damage and bodily injury caused during the job.
- Commercial auto liability, covering the moving trucks and vehicles used on-site.
- Workers’ compensation, covering injuries to the mover’s own crew while on the property.
- Cargo liability, when the building or customer specifically requests coverage for goods in transit.
Buildings commonly set a baseline general liability limit of $1,000,000 per occurrence, and some ask for higher limits or an umbrella policy on top of the standard lines. Municipal licensing guidelines for movers also often specify a minimum cargo liability, commonly at least $50,000 per shipment.
Beyond the coverage amounts, a handful of certificate fields are worth a close look: the certificate holder’s exact spelled name and address, the policy’s effective and expiration dates, the ADDL INSD and SUBR WVD columns (which indicate additional insured and waiver of subrogation status), a description of operations naming the specific job, and a cancellation notice clause, with any required notice period.
How to request and obtain an acceptable COI
Getting an acceptable certificate issued before moving day comes down to four steps, and skipping the first one is the most common reason certificates get rejected at the last minute.
- Ask building management for their exact requirements. Request a sample certificate or a written list naming the precise legal name and address they want listed as the certificate holder, plus any required coverage minimums.
- Forward that sample to your mover and the mover’s insurance agent. Flag any special language the building wants, such as “additional insured” or “waiver of subrogation,” since these often require a separate endorsement rather than a simple notation on the certificate itself.
- Give the agent time to issue the paperwork. Most insurance producers need 24 to 48 hours to generate a signed, typed ACORD 25 along with any requested endorsements, so start this step as soon as a move date is confirmed.
- Send the finished COI to building management and confirm it’s accepted. If management rejects it, ask them to state the specific deficiency in writing (a missing endorsement, wrong certificate holder name, insufficient limits) so the mover’s agent can fix exactly what’s wrong rather than guessing and resubmitting blind.
Pro Tip: Request the building’s COI requirements the same day you book your mover, not the week before. Endorsements like additional insured status sometimes take longer to process than a standard certificate.
Buildings that handle a steady stream of move-ins and move-outs, including most apartment complexes, tend to have this process down to a routine, which is one more reason apartment movers who’ve worked that specific building before can save you a round of back-and-forth. The same logic applies to office relocations, where freight elevator reservations and after-hours access often hinge on the certificate being accepted first.
How to check a COI is acceptable
Once a certificate lands in your inbox, a few checks separate one that will clear building security from one that bounces back.
- Confirm the certificate holder’s name and address match the building’s sample exactly, and that the policy dates cover your actual move date.
- Check the ADDL INSD and SUBR WVD boxes. A certificate that merely lists the building as certificate holder doesn’t automatically grant additional insured rights; that status usually requires a formal endorsement attached to the policy.
- Look for a signed, typed document with no handwritten corrections, limits that meet or exceed the building’s stated minimums, and cancellation language that meets the building’s notice requirements.
A handful of red flags tend to repeat: expired policy dates, an insured name that doesn’t match the mover’s legal business name, a broker who won’t take a follow-up call, or a certificate someone filled in by hand. Some municipal guidance calls for typed certificates without handwritten corrections, which is one reason buildings may reject handwritten COIs rather than asking for a correction.
How a COI differs from protection for your belongings
A COI and valuation coverage solve two completely different problems, and mixing them up is where most moving-day confusion starts. Federal rules require movers on interstate jobs to offer two options for protecting your household goods, separate from any building insurance requirement.
- Released Value Protection is included at no extra charge but caps liability at $0.60 per pound per article.
- Full Value Protection makes the mover responsible for an item’s replacement value, usually for an added cost and sometimes with a deductible.
- Third-party insurance is available separately for customers who want coverage beyond either standard option.
The gap between the two options shows up fast with electronics. A 10-pound item valued at $1,000 would net only $6 in compensation under Released Value (60 cents times 10 pounds), which is why many movers point customers toward Full Value Protection or added coverage for anything with real value. None of this overlaps with the building’s COI, which only ever covers damage to the property itself.
How we handle COI requests for our customers
When a building asks for a certificate of insurance, we work directly with you and the property manager to match the exact wording they need, right down to the certificate holder’s name and address. We confirm the building has accepted the document before move day, so there’s no surprise at the loading dock or freight elevator. As a licensed moving company, we build that same clear communication into packing and handling details throughout the job, keeping you informed from the first call to the final box.
— Ilya
Get your move booked with COI handling included
If your building requires a certificate of insurance, we can help coordinate the details. We request the building’s exact wording, follow up with their management office, and confirm acceptance so your crew isn’t stuck in the lobby on moving day.
Here’s what to do when you reach out:
- Mention your building’s COI requirements, or a sample certificate if you have one, when you request your quote.
- Tell us your move date early so our insurance producer has time to issue endorsements if the building needs additional insured or waiver of subrogation language.
- Browse our full range of services, from office relocations to apartment moves, to find the one that matches your situation.
Visit ShipShape Moving to get a quote and let us know your building’s certificate requirements before your move date locks in. For long-distance moves with their own valuation choices, our long-distance moving team walks you through Full Value Protection and Released Value before the truck ever gets loaded, and if a long-distance or specialty load needs a dedicated crew and a binding estimate, small-load moving services built around single-team logistics are worth comparing too.
FAQ
Do I need a certificate of insurance for moving?
You need one only if your building, property manager, or HOA requires it, which is common in high-rises, condos, and commercial buildings with freight elevators or shared common areas. Check with building management before move day, since movers can be denied entry or elevator access without an accepted certificate on file.
What does COI mean for movers?
COI stands for certificate of insurance, a document proving the moving company carries active liability and workers’ compensation coverage. It protects the building and its property, not your personal belongings, which are covered separately under valuation protection.
Where do I get my certificate of insurance?
Your moving company’s insurance agent or producer issues the COI, typically within 24 to 48 hours of being given the building’s exact requirements. When you book with us, we coordinate the certificate process with you and the building.
Can I make my own certificate of insurance?
No, a certificate of insurance has to come from the moving company’s insurance producer or agent, since it certifies that specific policies are active and lists real coverage limits and dates. A certificate someone fills in by hand or without the issuing agent’s involvement is a common reason buildings reject the document outright.